Commercial Real Estate (CRE) Finance in India
Explore commercial property financing solutions for offices, retail spaces, warehouses, industrial properties, commercial projects and rental-income-generating assets. Compare available lender options and get application assistance across India.
Apply Online Now → Calculate EMI Compare Loan OptionsWhat is Commercial Real Estate Finance?
Commercial Real Estate (CRE) Finance refers to debt or equity capital provided to purchase, develop, construct or refinance income-producing and non-residential properties. It can support businesses, investors, developers and property owners seeking funding for commercial assets.
Office Buildings
Financing assistance for office premises, business centres and commercial workspaces.
Retail & Showrooms
Explore funding for shops, showrooms, retail outlets and shopping complexes.
Industrial Properties
Funding options for industrial buildings, manufacturing premises and plants.
Warehouses
Financing assistance for logistics parks, storage facilities and warehouses.
Commercial Construction
Explore project-based funding for eligible commercial construction and development.
Rental Income Properties
Options for eligible income-generating commercial properties and leased assets.
Commercial Real Estate Loan Interest Rates & Lenders
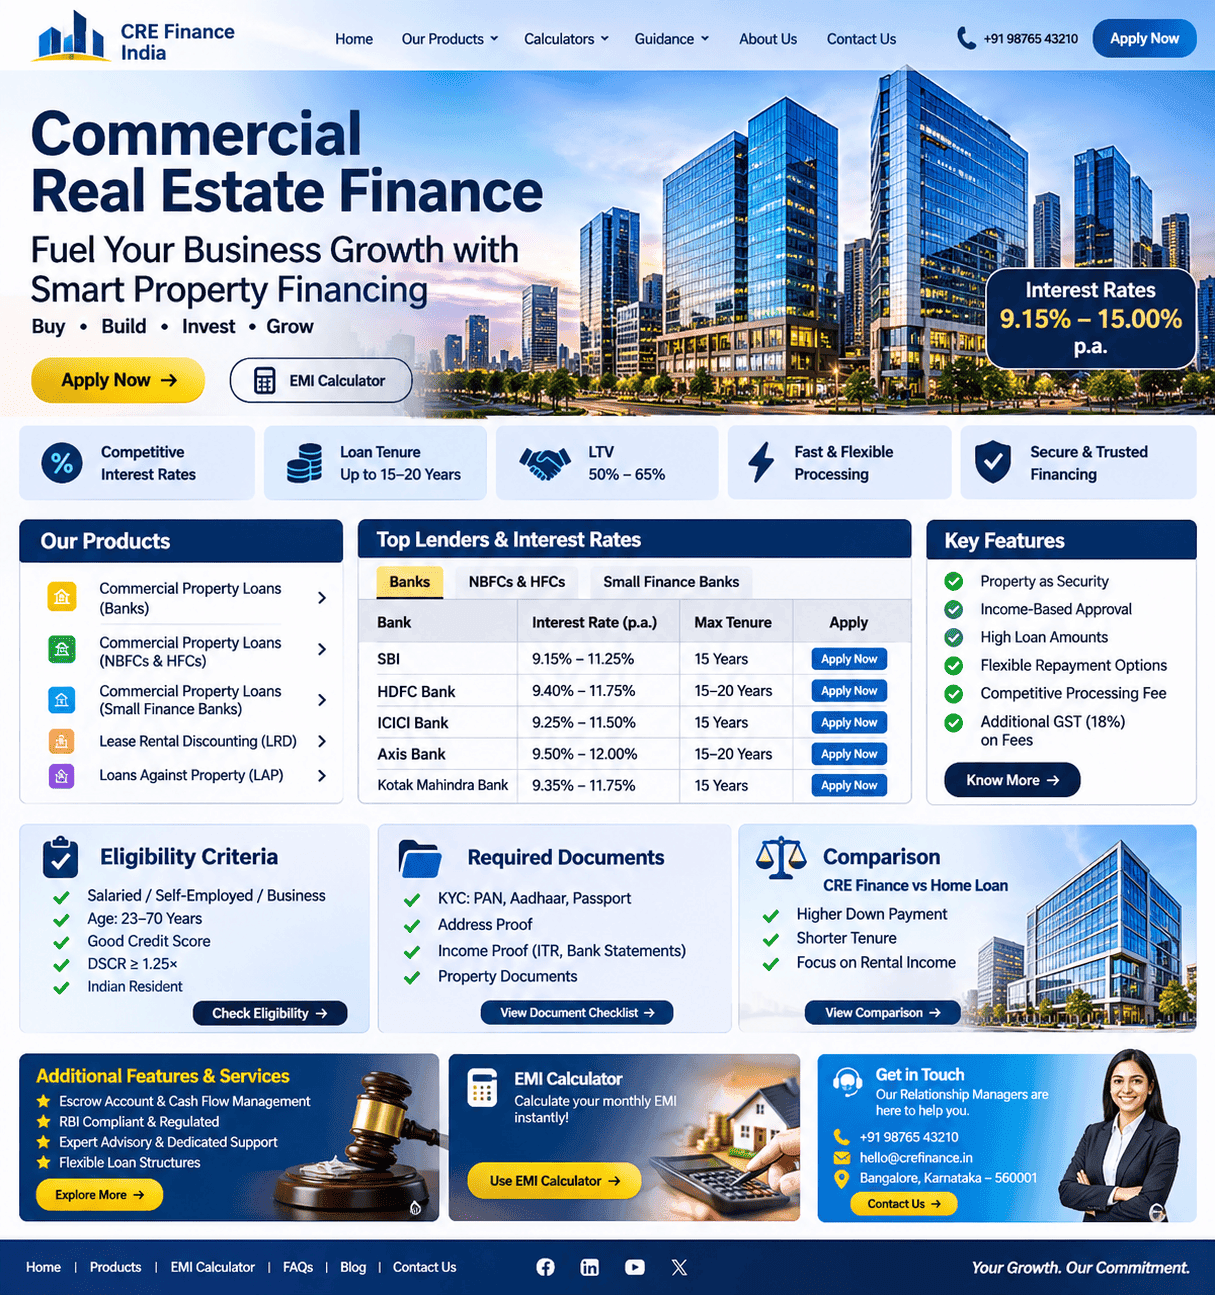
Explore the lender-wise indicative loan amounts, tenure, interest rates and processing fees supplied in the reference information. Actual terms must be confirmed directly with the concerned lender.
1. Commercial Real Estate Loans – Public & Private Banks
Commercial banks may offer competitive pricing and larger loan facilities, subject to property valuation, borrower eligibility, project feasibility and lender policy.
| Bank | Minimum Loan | Maximum Loan | Loan Tenure | Interest Rate (p.a.) | Processing Fee | Apply / EMI |
|---|---|---|---|---|---|---|
| State Bank of India (SBI) | ₹25 Lakh | ₹500+ Crore (Project-based) | Up to 15 Years | 9.15% – 11.25% | 0.25% – 1.00% (Min ₹10,000) | Apply NowEMI Calculator |
| HDFC Bank | ₹50 Lakh | Up to ₹10 Crore+ | Up to 15–20 Years | 9.40% – 11.75% | Up to 1.25% – 1.50% (Min ₹4,500) | Apply NowEMI Calculator |
| ICICI Bank | ₹50 Lakh | Up to ₹10 Crore+ | Up to 15 Years | 9.25% – 11.50% | 0.50% – 1.00% | Apply NowEMI Calculator |
| Axis Bank | ₹50 Lakh | Up to ₹10 Crore+ | Up to 15–20 Years | 9.50% – 12.00% | 1.00% – 1.50% (Min ₹10,000) | Apply NowEMI Calculator |
| Kotak Mahindra Bank | ₹50 Lakh | Up to ₹10 Crore+ | Up to 15 Years | 9.35% – 11.75% | Up to 1.00% | Apply NowEMI Calculator |
| Punjab National Bank (PNB) | ₹25 Lakh | Up to ₹10 Crore+ | Up to 10–12 Years | 9.25% – 11.50% | 0.50% – 1.00% (Min ₹10,000) | Apply NowEMI Calculator |
2. Commercial Real Estate Loans – NBFCs & HFCs
NBFCs and HFCs may offer different underwriting approaches and customised property finance structures. Pricing, turnaround time and conditions vary by lender and case.
| NBFC / HFC | Minimum Loan | Maximum Loan | Loan Tenure | Interest Rate (p.a.) | Processing Fee | Apply / EMI |
|---|---|---|---|---|---|---|
| Bajaj Finance / Bajaj Housing | ₹25 Lakh | Up to ₹15 Crore | Up to 15–20 Years | 10.25% – 14.00% | Up to 2.00% | Apply NowEMI Calculator |
| PNB Housing Finance | ₹25 Lakh | Up to ₹10 Crore | Up to 12–15 Years | 9.75% – 12.25% | 0.75% – 1.00% (Min ₹15,000) | Apply NowEMI Calculator |
| Tata Capital | ₹10 Lakh | Up to ₹7.5 Crore | Up to 12 Years | 10.50% – 13.50% | Up to 1.50% – 2.00% | Apply NowEMI Calculator |
| Aditya Birla Finance | ₹25 Lakh | Up to ₹10 Crore | Up to 12 Years | 11.00% – 14.00% | Up to 2.00% | Apply NowEMI Calculator |
| L&T Finance | ₹20 Lakh | Up to ₹5 Crore | Up to 10–12 Years | 10.75% – 13.50% | Up to 1.50% | Apply NowEMI Calculator |
| Godrej Capital | ₹20 Lakh | Up to ₹10 Crore | Up to 15 Years | 10.50% – 13.00% | Up to 2.00% | Apply NowEMI Calculator |
3. Commercial Real Estate Loans – Small Finance Banks (SFBs)
Small Finance Banks may cater to eligible MSMEs, self-employed applicants and smaller commercial property requirements, subject to their product policies.
| Small Finance Bank | Minimum Loan | Maximum Loan | Loan Tenure | Interest Rate (p.a.) | Processing Fee | Apply / EMI |
|---|---|---|---|---|---|---|
| AU Small Finance Bank | ₹2 Lakh | Up to ₹2 Crore – ₹5 Crore | Up to 15 Years | 10.50% – 14.50% | Up to 2.00% – 3.00% | Apply NowEMI Calculator |
| Equitas Small Finance Bank | ₹3 Lakh | Up to ₹2 Crore | Up to 12 Years | 11.50% – 15.00% | Up to 2.00% | Apply NowEMI Calculator |
| Ujjivan Small Finance Bank | ₹2 Lakh | Up to ₹1.5 Crore | Up to 10 Years | 12.00% – 16.00% | Up to 2.00% | Apply NowEMI Calculator |
| Jana Small Finance Bank | ₹3 Lakh | Up to ₹2 Crore | Up to 10 Years | 12.50% – 16.50% | Up to 2.50% | Apply NowEMI Calculator |
Types of Commercial Real Estate Finance
Commercial Property Purchase Loan
Funding assistance for eligible ready commercial offices, shops, showrooms and business premises.
Commercial Construction Finance
Project-linked funding for eligible commercial construction and development requirements.
Lease Rental Discounting (LRD)
Financing against eligible future rental receivables from leased commercial properties.
Loan Against Commercial Property
Explore mortgage-backed funding against an eligible existing commercial property.
Bridge Finance
Short-term funding assistance for eligible transitional or time-sensitive property requirements.
Property Loan Refinance
Explore balance transfer or refinancing possibilities, subject to lender assessment and charges.
Industrial Property Finance
Funding options for eligible factories, industrial premises and warehouses.
Retail & Office Space Finance
Financing assistance for eligible commercial retail units and office spaces.
Commercial Project Finance
Structured funding consideration for eligible larger commercial real estate projects.
Key Features of CRE Finance
Asset-Backed Security
The commercial property is generally mortgaged or charged as security, subject to legal and technical checks.
Income-Driven Assessment
Lenders may assess property cash flow, rental yield, business revenue and Debt Service Coverage Ratio (DSCR).
Loan-to-Value (LTV)
Funding is linked to the lender's assessed property value and applicable LTV limits. The borrower contributes the balance.
Flexible Loan Structures
Depending on the product, repayment can include term loans, construction-linked disbursements or rental receivable structures.
Recourse & Guarantees
Some facilities may require personal or corporate guarantees in addition to property security.
Escrow / TRA
Lenders may require rental or project cash flows to pass through an escrow or Trust and Retention Account.
Commercial Real Estate Loan Eligibility Criteria
Eligible Applicants
- Salaried individuals
- Self-employed professionals
- Business owners
- Partnership firms
- LLPs and private limited companies
- Eligible Special Purpose Vehicles (SPVs)
Typical Age Guidelines
- Salaried: Typically 23 to 70 years
- Self-employed: Typically 25 to 70 years
- Age at loan maturity is subject to lender policy
Financial Profile
- Satisfactory credit history
- Promoter/director credit assessment
- Appropriate business turnover
- Operational track record
- Repayment capacity and cash-flow assessment
Property Assessment
- Clear and marketable title
- Legal due diligence
- Technical valuation
- Approved building plans
- Applicable permissions and compliance
DSCR Assessment
A DSCR threshold of usually ≥ 1.25× may be considered in some cases. Actual requirement varies by lender, property and facility structure.
Residency
Indian residents and NRIs may be considered under applicable lender and banking guidelines.
Documents Required for CRE Finance
1. KYC & Identity Proof
- PAN Card
- Aadhaar Card
- Passport
- Voter ID
- Driving Licence
2. Address Proof
- Recent utility bills
- Aadhaar Card
- Passport
- Voter ID
3. Income & Financial Proof
- Last 2 to 3 years of ITRs
- Audited/provisional balance sheets
- Profit & Loss statements
- Personal and business bank statements for last 6 to 12 months
- Salary slips and Form 16, where applicable
4. Property Documents
- Title deeds and ownership chain
- Approved building plans/maps
- Encumbrance Certificate (EC)
- Latest property tax receipts
5. Rental & Project Documents
- Existing or projected rent rolls
- Lease agreements
- Project reports and cost estimates, where applicable
- Cash-flow projections
6. Technical & Legal Reports
- Independent technical valuation
- Legal search and title report
- Environmental compliance reports, where applicable
- Other documents as requested by lender
CRE Finance vs Residential Home Loan
| Feature | Commercial Real Estate (CRE) Finance | Residential Home Loan |
|---|---|---|
| Primary Purpose | Business use, commercial operations or rental income generation | Personal housing / family dwelling |
| Underwriting Focus | Property cash flow, business revenue, DSCR and LTV | Borrower's personal salary/income and credit score |
| Interest Rates | Generally higher due to elevated commercial risk profile | Typically lower retail interest rates |
| Down Payment / LTV | Higher equity contribution required (25%–50% down) | Lower down payment options available (often 10%–20%) |
| Loan Tenure & Terms | Shorter terms (5–10 years), periodic balloon/refinance cycles | Long-term amortizations up to 20–30 years |
| Regulatory Risk Weight (RBI) | Subject to specific commercial real estate risk-weight norms | Classified under retail housing / priority sector norms |
Important Borrowing Considerations
- Loan-to-Value (LTV): Generally capped between 50% and 65% for commercial properties, as stated in the supplied indicative overview. Actual LTV depends on lender policy and property assessment.
- Eligible Use Cases: Purchase of ready or under-construction office spaces, retail outlets, warehouses, commercial plots, Lease Rental Discounting (LRD), or loans against existing commercial property (LAP).
- Applicable Taxes: Processing fees attract an additional 18% GST across all institutions, as stated in the supplied information. Applicable tax treatment should be confirmed with the lender.
- Escrow / Cash-Flow Ring-Fencing: Lenders may require an Escrow Account or Trust and Retention Account (TRA) to route rental or business revenues towards debt servicing.
- RBI / Regulatory Aspects: Commercial bank exposures to CRE are subject to applicable RBI prudential guidelines, risk-weight frameworks and capital adequacy requirements.
How to Apply for Commercial Real Estate Finance?
Submit Enquiry
Share Property & Financial Details
Explore Lender Options
Prepare & Submit Documents
Track Application Process
LoansBazaar India provides loan enquiry, lender-option comparison and application assistance. The lender independently evaluates the application and decides on sanction, disbursement and final terms.
Why Explore CRE Finance with LoansBazaar India?
PAN India Assistance
Enquiry and application assistance for eligible customers across India.
Multiple Lender Options
Explore potential financing options from banks, NBFCs and housing finance companies.
Option Comparison
Review available rates, tenure, loan amount and lender terms for your requirements.
Documentation Guidance
Assistance in understanding and preparing the documents requested by lenders.
Application Assistance
Support through the enquiry and application process.
15+ Years of Experience
Financial services experience and loan assistance across multiple categories.
Explore Other Loan Products
Explore loan assistance across personal, business, property, corporate and specialised financing categories.
🏗️ Project Finance
Project-based funding enquiries for eligible business and infrastructure projects.
Apply Now📑 Invoice Discounting
Working capital solutions against eligible trade receivables and invoices.
Apply Now🏭 Industrial Expansion Finance
Funding enquiries for eligible industrial expansion and capacity development.
Apply Now🏦 Structured Finance
Explore customised corporate funding structures for eligible financing requirements.
Apply NowFrequently Asked Questions – CRE Finance
1. What is a Commercial Real Estate (CRE) Loan?
A CRE loan is a financing facility for eligible non-residential properties such as offices, retail spaces, warehouses, industrial premises and commercial projects.
2. What is the typical interest rate for CRE finance in India?
The indicative range in the supplied lender overview is 9.15% to 15.00% p.a. Actual rates depend on the applicant, property, loan structure and lender's current policy.
3. What is the typical Loan-to-Value (LTV) ratio?
The supplied overview indicates a general LTV range of 50% to 65%. Actual funding depends on property valuation, legal status, borrower contribution and lender rules.
4. Can I get finance for a commercial property purchase?
Eligible applicants may explore finance for offices, retail outlets, warehouses and other commercial properties, subject to lender assessment.
5. What is Lease Rental Discounting (LRD)?
LRD is a financing structure where eligible rental receivables from leased property are considered for repayment assessment and loan structuring.
6. Can an existing commercial property be used as collateral?
Eligible existing commercial properties may be considered as security for a loan against property or another permitted facility.
7. What documents are generally required?
Typical documents include KYC, income and financial statements, bank statements, property title documents, approved plans, valuation and lease records where applicable.
8. Does LoansBazaar India directly approve or disburse the loan?
No. LoansBazaar India provides loan enquiry, comparison and application assistance. The concerned lender independently assesses the application and makes the final lending decision.
9. Can I calculate my CRE loan EMI online?
Yes. Use the LoansBazaar India EMI Calculator to estimate EMI based on loan amount, interest rate and tenure. The result is an estimate, not a lender quotation.
10. How can I apply online?
Submit your enquiry through the online application page. The team can assist with understanding available options and the application process.
Get Commercial Real Estate Finance Assistance
Share your commercial property and funding requirements. Explore available lender options with LoansBazaar India.
LoansBazaar India
Financial Services Provider & Corporate DSA Across India
15+ Years of Experience in Financial Services
📞 9702878434 | 9137420845
📍 Barwa Shuklpur, Meja, Prayagraj, Uttar Pradesh 212305, India
Business Hours: Monday–Friday, 9:00 AM–6:00 PM IST
Apply Online Now Calculate EMIImportant Disclaimer
The lender names, loan amounts, interest rates, tenure, LTV and processing fee ranges displayed on this page are indicative reference information supplied for general awareness and are not a confirmed or guaranteed offer from any bank, NBFC or HFC. These figures have not been independently verified as current lender offers. Product availability and terms may change without notice. Actual interest rates, loan amount, tenure, LTV, processing fees, GST, legal and valuation charges, eligibility and approval are determined solely by the concerned lender after reviewing the applicant's profile, income, credit history, property valuation, title, financial documents and applicable policies. A loan enquiry or application does not guarantee sanction or disbursement. LoansBazaar India operates as a financial services provider and Corporate DSA, offering loan enquiry, comparison and application assistance; it is not the lender. RBI and other regulatory requirements apply as relevant. Applicants should verify all current terms directly with the lender before making a financial decision.